
For eight years, the honest answer to “is Bitcoin legal in Pakistan?” was a shrug. No statute made owning it a crime, yet the State Bank of Pakistan had ordered every bank and payment company in the country to stay away from it. Pakistanis bought crypto anyway, in such numbers that Chainalysis ranked Pakistan third in its 2025 Global Crypto Adoption Index, behind only India and the United States, and second in the world for retail activity on centralized exchanges.
2026 ended the shrug. Parliament passed the Virtual Assets Act, which came into force on March 5. The State Bank replaced its 2018 prohibition in April. In August, the new regulator, PVARA, opened licensing and gave platforms already serving Pakistani users until September 5 to apply or shut down. The state stopped chasing users and started licensing the pipes. What it did not do is turn Bitcoin into money: the new law says plainly that virtual assets are not legal tender.
Bitcoin in Pakistan at a glance (September 2026)
- Owning Bitcoin: Not an offence. The 2026 Act regulates businesses that provide crypto services and the people who issue tokens, not individual holders.
- Legal tender: No. The Act’s own definitions rule that out.
- Regulator: Pakistan Virtual Assets Regulatory Authority (PVARA), created by ordinance in July 2025 and put on a permanent footing by the 2026 Act.
- Banks: Allowed since April 2026 to open accounts for PVARA-licensed crypto firms, but still barred from trading or holding crypto with their own money or customer deposits.
- Platforms: Firms operating on or before March 5, 2026 had to file for a No Objection Certificate by September 5, 2026. Running an unlicensed crypto service can mean up to five years in prison or a PKR 50 million fine.
- Tax: A 20% to 30% capital gains tax on crypto profits was on the table before Budget 2026-27. Confirm the enacted treatment with the FBR before filing.
Is Bitcoin legal in Pakistan in 2026? Yes, but the law targets platforms
The short answer is yes, with conditions that matter more than the headline. The text of the Virtual Assets Act, 2026 as passed by the National Assembly, published by PVARA, applies to two groups: anyone providing a virtual asset service “in or from Pakistan”, and anyone issuing a token from the country. A person who buys Bitcoin and keeps it in their own wallet is neither.
The service list in the Act’s schedule is broad. It covers advice, exchange, custody, broker-dealer work, lending and borrowing, derivatives, asset management, transfer and settlement, token issuance and mining services that touch customer money. Four provisions will shape how ordinary users experience the new regime:
- Offshore apps are not automatically out of reach. Section 4 lets PVARA act beyond Pakistan’s borders and set rules for when a foreign platform counts as serving people in Pakistan.
- Mining alone does not need a licence. Section 37 says pure mining is not a licensable service. Mining that handles customer funds is, and PVARA can require large operators to register based on scale, energy use or hash rate.
- Promotion is regulated too. Section 43 bars anyone from advertising a virtual asset unless the issuer is licensed or registered, and it requires risk disclosures in marketing material.
- Algorithmic stablecoins are out. Section 53 prohibits tokens that hold their value through an algorithm instead of adequate collateral, unless regulations specifically allow them.
The practical risk for a Pakistani user has changed shape. The offence of running an unlicensed service falls on the platform, not the customer. But a platform that misses the licensing process can be forced to stop, and customers of a shuttered exchange tend to learn about withdrawal queues the hard way. Checking a platform’s regulatory status now belongs alongside the other common crypto mistakes worth avoiding.
Bitcoin in Pakistan before 2018: Urdubit and a legal vacuum
Bitcoin started with Satoshi Nakamoto’s 2008 white paper, which described a way to send payments directly between people without a bank in the middle. A shared public ledger, the blockchain, records every transaction, and a network of computers verifies it. No central bank sets its supply or defends its price, which is why Bitcoin has spent its whole life swinging between euphoria and panic. TechEngage has a separate explainer on why Bitcoin’s price is so volatile.
Pakistan’s first serious attempt to build a local market came in 2014, when Urdubit opened as the country’s first Bitcoin exchange, built on BlinkTrade’s exchange software. The opening looked obvious to its founders: Pakistan receives billions of dollars from workers abroad, and a large share of its adults have never had a bank account.
Nobody in government had a position on any of this. Payments consultant Faisal Khan told The Express Tribune in February 2014 that Pakistan had no official stance on Bitcoin, and he argued that near-zero transaction costs were exactly what made it attractive. For four years, that vacuum was the policy.
April 6, 2018: the SBP circular that cut crypto off from banks
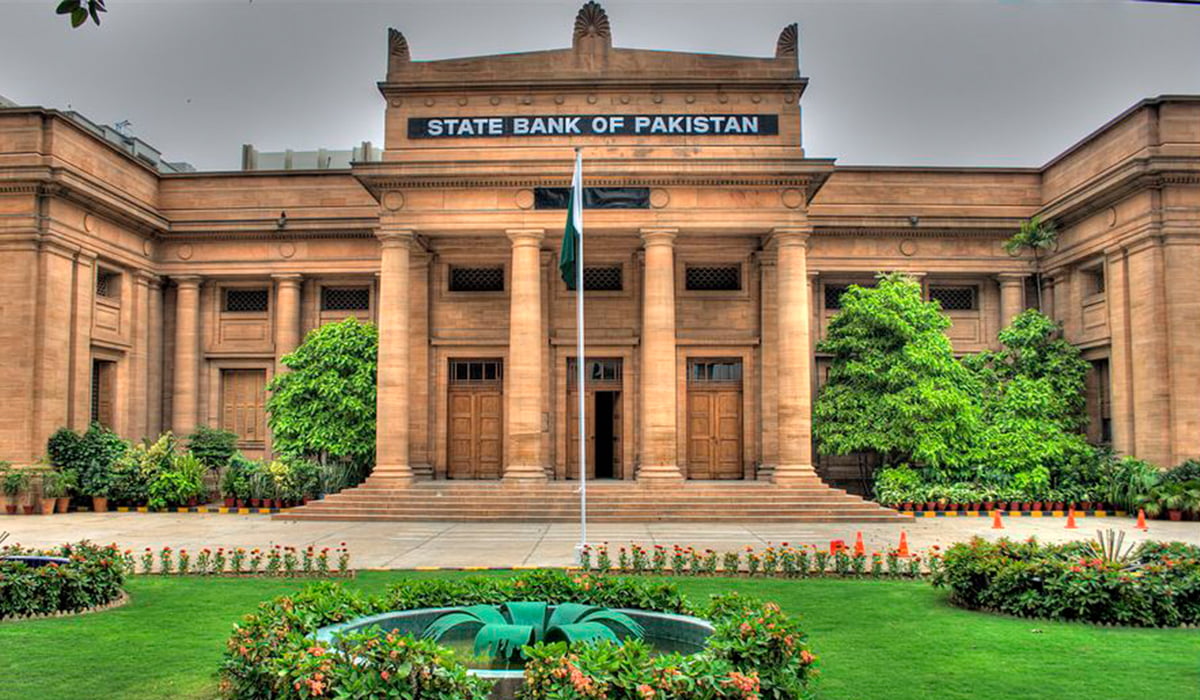
The vacuum closed on April 6, 2018. The State Bank issued BPRD Circular No. 03 of 2018, stating that it had not licensed anyone to issue, sell, buy, exchange or invest in virtual currencies. It told banks, development finance institutions, microfinance banks, payment system operators and payment service providers not to process, trade, hold, transfer, promote or invest in them, and not to help their customers do so. Any such transaction was to be reported to the Financial Monitoring Unit as suspicious.
Read carefully, the circular never criminalized owning Bitcoin. It instructed regulated financial institutions. In practice that distinction was academic, because a crypto market with no bank on-ramp can barely function. Urdubit announced it was closing within a day of the circular, telling users to withdraw their funds as quickly as possible. ProPakistani reported the SBP’s reasoning: virtual currencies offered a high degree of anonymity that could be used for illegal activity.
The result was the awkward arrangement that lasted until 2026. Holding crypto was not illegal, but moving rupees in and out of it through the formal banking system was. Demand did not disappear. It moved to platforms and payment routes the State Bank could not see.
2022 to 2023: Pakistan’s push for a complete crypto ban
The hardest line came through the courts. Responding to a petition filed by Waqar Zaka, the Sindh High Court asked for a formal view on whether crypto could operate legally. The committee that answered was chaired by SBP Deputy Governor Sima Kamil and included the Finance Division, the IT ministry, the SECP, the PTA and the Financial Monitoring Unit. Its report, covered by Dawn in January 2022, concluded that the risks of crypto in Pakistan outweighed the benefits. It cited speculation, capital flight and illicit transfers, and it recommended a complete ban, including action against exchanges such as Binance and OctaFX. The court sent the matter to the finance and law ministries for a joint decision.
By May 2023, the government sounded certain. At a Senate Standing Committee on Finance session, Minister of State for Finance Aisha Ghaus Pasha said “cryptocurrencies will never be legalized in Pakistan,” pointing to strict conditions set by the Financial Action Task Force, ProPakistani reported. The committee directed authorities to block crypto services and websites, and SBP officials told senators crypto would not receive legal status.
What the ban camp never produced was a law. No statute outlawing crypto passed Parliament, so enforcement stayed piecemeal while users kept signing up. Pakistan was never alone in trying this. A number of countries still enforce strict Bitcoin restrictions, and outright bans have a poor record of shrinking demand.
Is Bitcoin halal? Pakistan’s Shariah question is still open
For a Muslim-majority country with an Islamic banking sector, the religious question is not a sideshow. Scholars have never agreed on it. At a 2017 conference in Kazan, Medina Kalimullina, an adviser on Islamic finance to Russia’s Council of Muftis, said Shariah standards did not yet cover Bitcoin, and she listed excessive risk (maisir), uncertainty (gharar) and the absence of real assets or state guarantees as the main objections, according to a report carried by The Express Tribune. Matthew J. Martin of Indonesian fintech startup Blossom Finance took the other side in the same debate, arguing that Bitcoin as a payment network is halal.
Religious bodies elsewhere have gone further. In November 2021, Indonesia’s National Ulema Council declared crypto haram for use as currency, citing uncertainty, wagering and harm, although the ruling was not a legal ban on trading.
Pakistan’s new law does not settle the debate. It moves it inside the regulator. The Act defines a Shariah Advisory Committee, constituted by PVARA, to advise on Shariah matters, and its statement of objects lists the development of Shariah-compliant products among its goals. Until that committee publishes guidance, the religious status of Bitcoin in Pakistan remains a matter of individual scholarly opinion rather than regulation.
2025: Pakistan Crypto Council, 2,000 MW for mining and a Bitcoin reserve
The reversal was fast. On March 14, 2025, the government launched the Pakistan Crypto Council under Finance Minister Muhammad Aurangzeb, with a mandate to draft regulatory policy and bring blockchain and digital assets into the financial system. Bilal Bin Saqib became its chief executive.
Just over three weeks later, the council made its most controversial appointment. On April 7, 2025, the Finance Division named Binance founder Changpeng Zhao as a strategic adviser on regulation, infrastructure and adoption, Business Recorder reported. Aurangzeb framed it as a signal that Pakistan was open for innovation. It was a striking choice. Zhao had pleaded guilty in the United States in November 2023 to failing to maintain an effective anti-money laundering program at Binance and resigned as its chief executive, and a Pakistani government committee had recommended action against Binance only three years earlier. US President Donald Trump pardoned Zhao in October 2025.
In late May 2025, Saqib went further on stage at the Bitcoin 2025 conference in Las Vegas. He told the audience that Pakistan was allocating 2,000 megawatts of surplus electricity in a first phase to Bitcoin mining and AI data centres, and that it had created a government-led Strategic Bitcoin Reserve holding digital assets already in state custody, rather than coins bought on the market. The government did not say how much the reserve holds.
The power pledge ran straight into Pakistan’s lender of last resort. The IMF sought an explanation for why it had not been consulted before electricity was earmarked for mining, and asked how such an allocation could be made while crypto’s legal status was undecided. The concern is easy to understand. Proof-of-work mining is energy-hungry by design, which is the same problem that pushed Ethereum to cut its energy consumption, and cheap power for miners in a country with a fragile electricity sector is a subsidy question as much as a technology one.
The 2026 Act quietly gave the reserve a legal home. Section 38 allows the federal government to set up a wholly owned Strategic Digital Wallet Company to hold and manage the state’s virtual assets for its reserve objectives, and bars that company from serving private customers.
Virtual Assets Act 2026: PVARA licences and fines up to PKR 50 million
PVARA began life in July 2025 under the Virtual Assets Ordinance, 2025. An ordinance in Pakistan lapses unless Parliament converts it, and in early March 2026 lawmakers passed the Virtual Assets Act, 2026, making the regulator permanent. By then PVARA had already issued No Objection Certificates to Binance and HTX in December 2025, The Block reported.
Section 54 of the Act sets out the criminal penalties:
- Running an unlicensed virtual asset service: up to five years in prison, a fine of up to PKR 50 million, or both.
- Running an initial token offering in breach of the Act: up to three years, a fine of up to PKR 25 million, or both.
- Knowingly giving the Authority false or misleading information: up to three years, a fine of up to PKR 20 million, or both.
- Ignoring an order or decision of the Authority: up to one year, a fine of up to PKR 25 million, or both, plus administrative penalties.
The customer-protection sections are the more useful part for users who lived through Urdubit’s closure. Licensees must keep customer assets segregated from their own, and those assets do not form part of the firm’s estate if it goes insolvent (Section 24). They must also meet custody and key-management standards (Section 26), and furnish proof-of-reserves and audit reports to the Authority (Section 27). Section 66 requires every licensed provider to meet its obligations under Pakistan’s income tax law and FBR rules, which matters for the tax discussion below.
April 2026: SBP replaces its 2018 crypto ban with bank rules
A licensing law means little if licensed firms cannot open a bank account. That changed in mid-April 2026, when the State Bank issued a directive letting banks, microfinance banks and payment system operators open accounts for firms licensed by PVARA, CoinDesk reported on April 15. The directive replaced the April 2018 circular.
The new rules come with conditions. Banks must verify the licence and apply enhanced due diligence under anti-money laundering and counter-terrorist financing rules. Customer money has to sit in segregated rupee accounts, kept apart from the crypto firm’s own operating balances. And banks remain barred from investing in, trading or holding crypto with their own funds or customer deposits. Pakistan has opened a door for regulated crypto businesses, not invited banks into crypto speculation.
For users, this is the piece that actually changes daily life. The 2018 circular’s real damage was to on-ramps. A documented route from a bank account to a licensed exchange and back is the thing Pakistani crypto users have lacked for seven years.
PVARA’s September 5, 2026 deadline for crypto platforms
PVARA opened licensing on August 21, 2026. Businesses that were already providing virtual asset services in Pakistan on or before March 5, when the Act took effect, count as “transitional persons” and had until September 5 to apply for a No Objection Certificate. Carrying on without an application after that date is an offence under Section 70, Decrypt reported, citing the regulator.
An NOC is a first step, not a licence. The path runs roughly like this:
- Register a company in Pakistan under the Companies Act, 2017.
- Apply to PVARA for a No Objection Certificate, with the business, ownership, anti-money laundering and technology documents the regulator requires.
- Register with the Financial Monitoring Unit.
- Incorporate a local subsidiary.
- File the full virtual asset service provider licence application.
According to Dawn’s report on the deadline, PVARA said Pakistan had moved from primary legislation to notified regulations and an open licensing process in under six months. Speed on paper is one thing. The number that will matter is how many established platforms come through the process, and how many quietly stop serving Pakistani users.
If you use a crypto app in Pakistan, check whether the firm has applied to or been cleared by the regulator. The PVARA website is the place to start. A platform that ignored the deadline is now operating outside the law, and that is a risk to your funds regardless of how good its app looks.
Crypto tax in Pakistan: the proposed 20% to 30% capital gains rule
Licensing and bank accounts make crypto visible, and visible income gets taxed. Ahead of Budget 2026-27, the government planned to expand Section 37 of the Income Tax Ordinance, 2001, to bring gains from crypto trading into the capital gains tax net at a rate expected to fall between 20% and 30%, ProPakistani reported on June 2, 2026. The plan followed consultations with the IMF, and a high-level committee also recommended ways to document crypto transactions and identify unregistered market participants.
The Finance Act 2026 was enacted on June 27 and took effect from July 1, according to KPMG Pakistan’s brief on the Finance Act. The final crypto rate and how it is calculated should be checked against the enacted text or with a tax adviser, because pre-budget proposals often change before they become law. The direction is not in doubt. Section 66 of the Virtual Assets Act already obliges licensed platforms to comply with FBR requirements, so regulated exchanges are set to become a major source of data for the tax authorities.
Why 40 million crypto accounts forced Pakistan’s policy change
The simplest explanation for the U-turn is scale. PVARA Chairman Bilal Bin Saqib told a Senate committee on August 31, 2026 that nearly 40 million Pakistanis hold crypto accounts, many of them opened before any regulation existed. That figure counts accounts, not verified unique people, so it overstates the number of active investors. Even so, it describes a market too large to shut down by circular.
Set that against how many Pakistanis use formal finance at all. The World Bank’s Global Findex 2025 data shows:
- Adults with a financial account, 2024: 27.3% in Pakistan, against 77.6% across South Asia.
- Adults with a financial account, 2021: 21.0% in Pakistan.
- Adults who own a mobile phone, 2024: 62.9% in Pakistan.
- Adults who own a smartphone, 2024: 32.4% in Pakistan.
Those numbers explain both sides of the argument. For the State Bank, a crypto market growing in a population that mostly sits outside banks looks like a documentation and capital-flight risk. For the government, the same population is a reason to pull that activity into a licensed system where it can be monitored and taxed.
Money from abroad raises the stakes further. Pakistan received a record $41.6 billion in workers’ remittances in fiscal 2026, up 8.6% from $38.3 billion a year earlier, Dawn reported using State Bank data. Any payment channel that can move value across borders outside the banking system touches one of the country’s most important sources of foreign exchange. Licensing crypto is partly a bet that it is safer to watch those flows than to pretend they are not happening.
What comes next for Bitcoin in Pakistan
Pakistan now has a law, a regulator, bank access and a deadline. What it does not yet have is a track record, and these are the pressure points to watch:
- Full licences: Binance and HTX hold NOCs, but the first full licences will show whether global exchanges are prepared to incorporate locally and live under PVARA supervision.
- Tax detail: The final capital gains rules, and how FBR uses data from licensed platforms, will shape whether users trade on licensed exchanges or drift back to unregulated channels.
- Mining power: The 2,000 MW plan still needs an answer the IMF can live with, and PVARA has yet to publish thresholds for registering large mining operations.
- Reserve transparency: Pakistan has not publicly disclosed how much Bitcoin its strategic reserve holds. Until it does, the reserve is a political statement more than a balance-sheet asset.
- Shariah guidance: Rulings from PVARA’s Shariah Advisory Committee could matter more to many Pakistani savers than any licence.
The broader shift is already done. In 2018 the state’s answer to Bitcoin was to cut it off from banks, and in 2023 a minister promised it would never be legal. By September 2026 it had a licensing portal and a criminal penalty for platforms that refuse to register. Bitcoin is still volatile, still not legal tender and still risky for anyone who cannot afford to lose what they put in. What changed is that Pakistan finally has rules for it.
This article explains law and policy in Pakistan. It is not financial, legal or tax advice. Crypto prices can fall sharply, so verify a platform’s PVARA status and your tax position before you invest.
Bitcoin in Pakistan: frequently asked questions
Is Bitcoin legal in Pakistan in 2026?
Yes. Owning Bitcoin is not an offence, and the Virtual Assets Act, 2026 regulates the businesses that offer crypto services through PVARA licences. Bitcoin is not legal tender, and running an unlicensed crypto service can bring up to five years in prison or a PKR 50 million fine.
Did the State Bank of Pakistan lift its crypto ban?
Yes, for licensed firms. In April 2026 the SBP replaced its 2018 circular with a directive that lets banks open accounts for PVARA-licensed crypto companies. Banks still cannot trade or hold crypto with their own funds or customer deposits.
What is PVARA?
PVARA is the Pakistan Virtual Assets Regulatory Authority. It was set up by ordinance in July 2025, made permanent by the Virtual Assets Act, 2026, and licenses exchanges, custodians, brokers, token issuers and other crypto service providers.
What was PVARA’s September 5 deadline?
Crypto businesses already serving Pakistan on or before March 5, 2026 had to apply to PVARA for a No Objection Certificate by September 5, 2026. Operating without an application after that date is an offence under Section 70 of the Act.
Is crypto taxed in Pakistan?
A capital gains tax of 20% to 30% on crypto trading profits was proposed ahead of Budget 2026-27 through an expansion of Section 37 of the Income Tax Ordinance, 2001. Check the enacted Finance Act 2026 or a tax adviser for the final rate.
Does Pakistan have a Bitcoin reserve?
Yes. Pakistan announced a Strategic Bitcoin Reserve in May 2025, seeded with digital assets already in state custody. The government has not publicly disclosed how much Bitcoin the reserve holds.
Is Binance licensed in Pakistan?
Binance received a No Objection Certificate from PVARA in December 2025, as did HTX. An NOC is preliminary clearance rather than a full licence, so both exchanges still have to complete PVARA’s licensing process.

Very useful blog .my question is what is the alternative of bitcoin